One lender said no.
That's not always the final answer.
 Tanner Cook NMLS #2090424Cornerstone First Mortgage, LLC NMLS #1738554.89 · 45 reviews of Tanner Cook on Experience.com
Get a fast second look from Tanner Cook at Cornerstone First Mortgage, LLC: in-house underwriting on most loans, no extra lender overlays, and 25+ non-QM investors to match your file to.
A second look is a review of your options, not a guarantee of approval.
Real estate agent? Send your buyer's scenario
Can your loan still be saved?
Six quick questions. No credit pull, no application, no obligation.
What's going on with your loan?
What went wrong?
Pick the reason closest to yours. Each page explains why lenders say no for it, and the realistic ways a second look may get around it.
- Denied in underwritingYou had a pre-approval letter and a contract, then underwriting said no. Here’s what usually changed and how to get the file reviewed fast.
- Self-employed incomeYour business makes money, but your tax returns say otherwise. See how underwriters read self-employed income and which other documents may work.
- Debt-to-income too highYour debts looked too large next to your income. The ratio depends on what gets counted and which guideline set is used, and both can change.
- Credit score too lowYour score was below the lender’s cutoff. That cutoff may be the lender’s own rule, and the score itself may be fixable sooner than you think.
- Bankruptcy or foreclosureA past credit event is still inside a waiting period. Check how the date was measured and whether another program sees it differently.
- New job or recent 1099You changed jobs, or your employer moved you to 1099, and the lender wants more history. Some programs look at this differently.
- No Social Security numberMany lenders simply don’t offer loans to borrowers with an ITIN. That’s a product gap at that lender, not a final answer.
- Not enough for down paymentThe lender said you’re short on funds, or couldn’t verify where your money came from. Both problems can sometimes be solved.
- Appraisal came in lowThe home appraised below the contract price, so the loan no longer fits. There are a few ways to close the gap, and one formal way to challenge the number.
- Condo not warrantableYour credit and income were fine, but the condo project failed review. The problem is the building, and some loan types look at it differently.
- Rental income not countedThe rent your properties earn didn’t count, or counted as a loss. How the rent is documented decides what the underwriter can use.
- Lender overlaysSome denials come from a lender’s own stricter rules, not the FHA, VA or Fannie Mae guideline. If that’s your file, another lender may see it differently.
One lender's no reflects that lender's rules and guidelines. Another may see the file differently.
Different lenders can use different guidelines, count income differently, and add rules of their own. Sometimes the answer is still no, because the program itself or the numbers don't work. Here's what's behind a second look with Tanner.
Underwritten in-house
Cornerstone underwrites most loans with its own underwriters, so a hard file gets a real answer from the people making the decision, not a bank three states away.
No extra lender overlays
Some denials come from a lender’s own rules stacked on top of the guideline. Cornerstone underwrites to the agency or investor guideline as written.
25+ non-QM investors
As a delegated correspondent, Cornerstone works with more than 25 non-QM investors, so a complex file can be matched to the guideline that fits it instead of being forced through one rulebook.
A scenario desk
Complex files can be structured before they are submitted, so the answer is known before a buyer is tied up in a contract for weeks.
Approvals that are already underwritten
Buyers can be fully underwritten before they pick a home. That is a different thing from a pre-qualification letter, and it may help surface problems before you are under contract. The approval is still conditional.
The appraisal may come with you
An existing appraisal can sometimes be transferred to a new lender. It depends on the investor and on how it was ordered, so it gets checked on day one.
Not every file can be saved, and every program has its own eligibility rules. When the answer is no, you'll hear it quickly, with the reason.
How a second look works
Fast, specific, and honest about what can and can't be fixed.
- Step 1
Tell us what happened
A one-minute rescue check: what the lender said, how you earn, and when you close. No credit pull to start.
- Step 2
We find the real reason
The denial notice or conditions list tells us the exact problem. We recheck the income, debts, credit and property from scratch.
- Step 3
We match the guideline
Your file is checked against agency programs and Cornerstone’s 25+ non-QM investors, and most files are underwritten in-house without extra lender overlays.
- Step 4
A plan, or an honest no
If it can be saved, you get the program, the document list and a realistic timeline. If not, you’ll know why and what would change it.
Real estate agent with a deal on the line?
Your buyer got denied, the approval shrank, or the lender went quiet. Send Tanner the scenario and get a straight answer on whether it can be saved.
One loan officer, from the first call to the closing table.
Tanner Cook is licensed in Arizona, Michigan, Texas and Washington, and reviews every second-look request for a property in those states himself. He works with Cornerstone First Mortgage, LLC (NMLS #173855), which underwrites most loans in-house and can match a hard file to agency programs or to more than 25 non-QM investors. You and your agent deal with Tanner directly from start to finish.
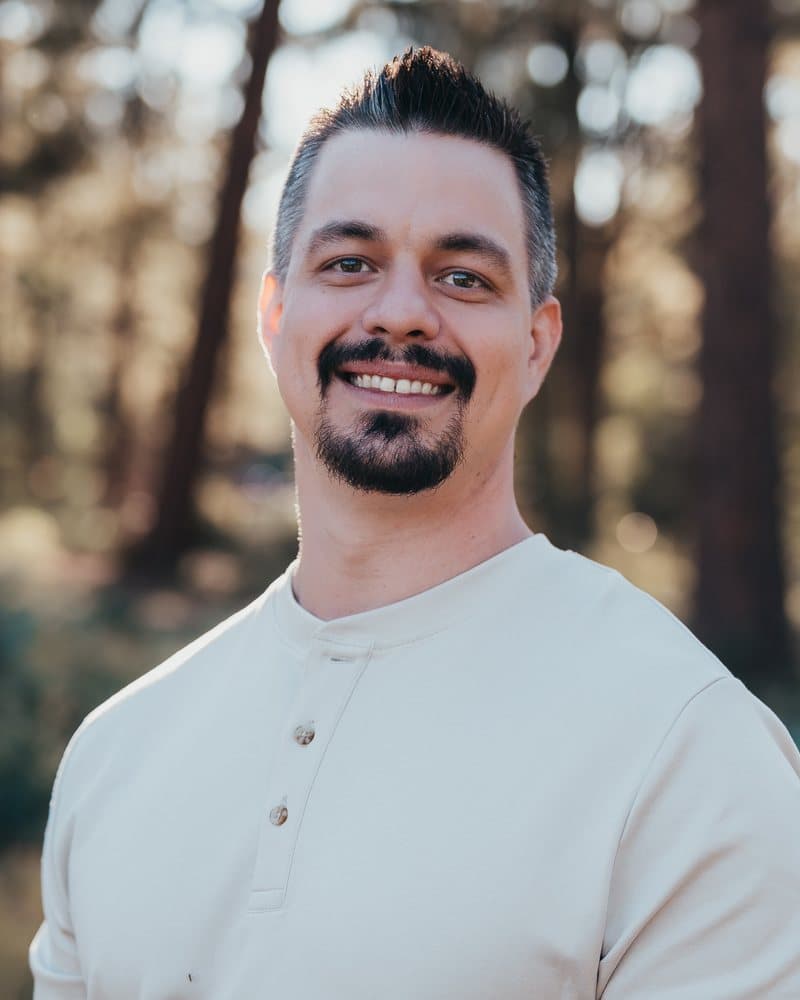
Tanner Cook
Mortgage Loan Originator
Tanner works the files other lenders turned down or let stall: self-employed and 1099 income, ITIN borrowers, investors, tight debt-to-income, condos, and deals with a closing date on the line. He finds out exactly why the answer was no, checks the file against the agency and non-QM guidelines Cornerstone can underwrite in-house, and tells buyers and their agents straight whether it can be saved.
Real clients. Real closings.
Reviews from buyers and real estate agents who worked with Tanner Cook.
4.89 · 45 reviews of Tanner Cook on Experience.comGuides for after a denial
All guides- When a Buyer's Financing Falls Apart: An Agent's Playbook
- Mortgage Options After a Denial: How Non-QM Loans Work
- Can You Switch Mortgage Lenders While Under Contract?
- Denied in Underwriting After Pre-Approval: Why It Happens
- What Is a Lender Overlay? Why One Lender Says No
- Pre-Qual vs. Pre-Approval vs. Underwritten Approval
After a denial: common questions
Straight answers to what buyers and agents ask when a loan goes sideways.
Sometimes, yes. A denial means that lender, with its guidelines and its own extra rules, could not approve the file as it was submitted. Another lender may be able to use a different guideline set, document your income differently, or remove a rule the first lender added on top of the guideline. It depends on the exact reason, so the first step is getting that reason in writing.
An overlay is a lender’s own requirement stacked on top of the official agency or investor guideline, such as a stricter credit, income or property rule than the guideline itself requires. Overlays are a common reason one lender says no while another says yes. Cornerstone underwrites to the agency or investor guideline as written rather than adding its own overlays.
Yes. Under the Equal Credit Opportunity Act and Regulation B, a lender that denies a completed application must give you a written notice with the specific reasons, or tell you how to request them. That notice is the most useful document you can send us, because the exact reason decides which fix fits.
Often, yes, but timing matters. A new lender needs a new application and new disclosures, and the appraisal may or may not be transferable depending on the investor and how it was ordered. Call as early as possible and share your closing date, and talk to your agent or attorney about your financing contingency deadline.
Non-QM programs can document income without relying on tax returns: 12 or 24 months of bank statements, a 12-month profit and loss statement prepared by a CPA or tax preparer, 1099s, a written verification of employment, or eligible assets. Each program has its own requirements and not everyone will qualify.
Talking through your situation and taking the rescue check does not require a credit pull. If you decide to apply, the lender will review your credit with your permission, and we will tell you before that happens.
Cornerstone First Mortgage, LLC (NMLS #173855) is the licensed mortgage lender Tanner Cook originates through. It underwrites most loans in-house and works with more than 25 non-QM investors as a delegated correspondent, alongside agency programs like FHA, VA, USDA and conventional loans. Tanner is licensed in Arizona, Michigan, Texas and Washington, so second looks on this site are for properties in those four states.
Then we tell you quickly and plainly, explain why, and lay out what would change the answer, such as paying down a debt, more time in business, a co-borrower, or a different property. A fast, honest answer gives you and your agent time to act. Ask your agent or attorney what your financing contingency means for your deposit.
Still have questions? Talk it through with Tanner. No application required. (469) 405-2690
The sooner Tanner sees the file, the more options are left.
Contract deadlines don't wait. Take the one-minute rescue check, or call or text now.
Prefer a scheduled call? Book 15 minutes with Tanner